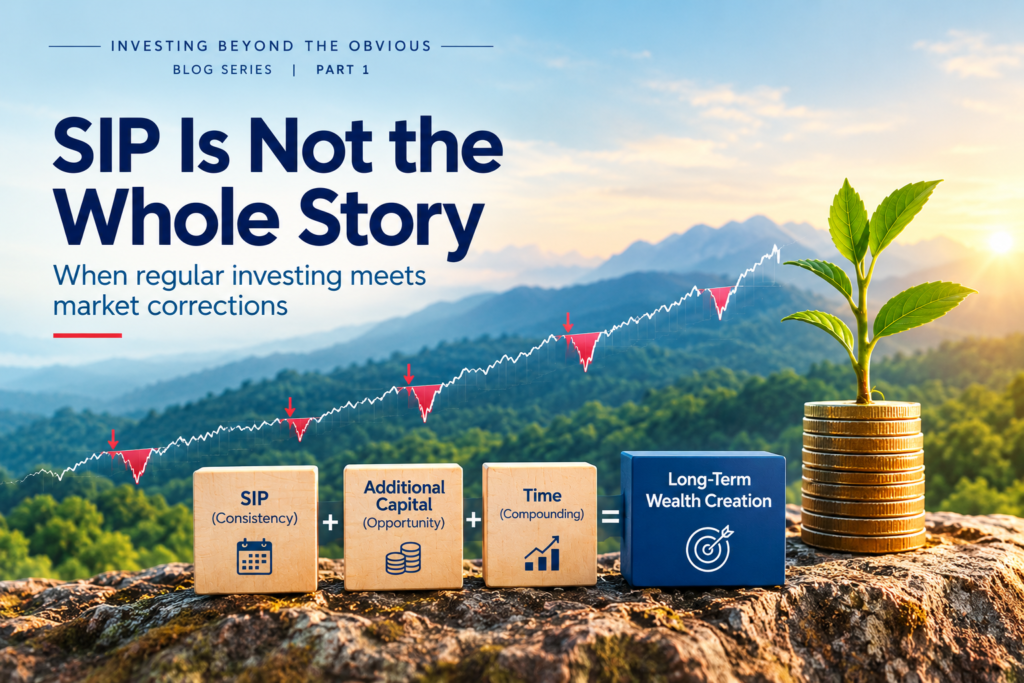
SIP Is Not the Whole Story
A regular SIP can provide consistency through market cycles. But when meaningful corrections occur, having additional long-term capital and a predefined plan may create another opportunity—without trying to predict the market bottom.
We have all heard it:
There is good reason for that advice.
But is that the whole story?
What happens when the market falls 10%, 15% or 20%? Should a long-term investor simply continue the regular SIP—or could a meaningful correction also be an opportunity to invest additional capital?
The answer does not require predicting the bottom.
It requires something much simpler:
SIP gives you something extremely valuable: consistency
A regular SIP creates a process. Every month, a fixed amount is invested irrespective of whether markets are rising, falling or moving sideways.
When prices are high, the SIP buys fewer units. When prices fall, the same amount buys more units. That simple mechanism allows an investor to participate through different market cycles without having to make a fresh investment decision every time the market moves.
And India's equity markets have provided plenty of such cycles. The NIFTY 50 has experienced deep corrections, sharp recoveries and long periods of compounding.

Chart source: TradingView chart supplied by the author. The chart is illustrative and is not a recommendation or forecast.
📌 What the chart makes visible
The long-term journey has not been a straight line upward. There have been repeated corrections, including declines of more than 20%, 30% and, during major crises, more than 50%.
Yet those corrections became part of a much longer investment journey. That is one reason why time in the market matters.
But what happens when the market corrects sharply?
This is where SIP may not be the whole story.
Investor A invests ₹10,000 every month in a NIFTY 50 ETF.
Investor B does exactly the same, but also keeps a predefined amount of additional capital available specifically for significant market corrections.
The precise levels are less important than the process.
That is very different from trying to predict the exact bottom.
2020: A useful example of what a correction can offer
The COVID-19 market collapse offers one of the clearest illustrations. The NIFTY 50 touched 12,362.30 on 14 January 2020 and fell to 7,610.25 on 23 March 2020—a decline of approximately 38.4%. By the end of 2020, it had recovered to 13,981.75.
Now imagine an investor had established a simple rule beforehand:
14 Jan 2020
| Illustration | Approximate level / value |
|---|---|
| NIFTY 50 peak | 12,362.30 |
| 20% correction level | 9,889.84 |
| Additional investment | ₹1,00,000 |
| Units at 20% correction | ~10.11 index-equivalent units |
| NIFTY 50 on 31 Dec 2020 | 13,981.75 |
| Illustrative value at year-end | ~₹1.41 lakh |
This is not a prediction model, and 20% is not a magical number. It simply demonstrates what can happen when additional capital is available during a meaningful correction.
Nobody knew on 23 March that the market had reached its low. The market did not announce: “This is the bottom.”
The point is therefore not to suggest that investors should buy at the exact low. It is to show the potential value of having a framework for deploying additional capital as prices fall.
What if the market falls further?
A 20% fall does not mean the market cannot fall another 10%. That is why trying to make one perfect “buy the dip” decision can simply become another form of market timing.
A more systematic approach can involve staged deployment:
| Market correction | Illustrative deployment of correction reserve |
|---|---|
| -10% | 20% |
| -15% | 30% |
| -20% | 30% |
| -25% or deeper | 20% |
Illustration only: this is not a prescribed investment strategy. The appropriate approach depends on an investor's goals, liquidity, risk tolerance, asset allocation and investment horizon.
Your SIP is already buying more when markets fall
A regular SIP is already doing something valuable during a correction.
| Price | ₹10,000 monthly investment buys |
|---|---|
| ₹10,000 | 1.00 unit |
| ₹8,000 | 1.25 units |
| ₹5,000 | 2.00 units |
The amount invested each month has not changed. The price has.
That is why SIP is not the whole story—but it remains an important part of the story.
The same principle applies beyond an index ETF
Consider HDFC Flexi Cap Fund, launched on 1 January 1995. According to HDFC Mutual Fund's August 2026 factsheet, a ₹10,000 monthly SIP in the Regular Plan – Growth Option since inception involved total contributions of ₹38 lakh and had a market value of approximately ₹22.96 crore as of 31 August 2026. The reported SIP return was 20.34%.
Over the last 15 years, the same ₹10,000 monthly SIP involved contributions of ₹18 lakh and had grown to approximately ₹67.67 lakh, representing an annualised SIP return of 16.07%.
📌 What these figures do—and do not—tell us
They demonstrate the historical effect of staying invested over long periods through multiple market environments. They do not imply that similar returns should be expected in the future.
For context, HDFC reports benchmark SIP returns of 14.56% since inception and 13.83% over 15 years for the NIFTY 500 TRI benchmark, while the additional benchmark figures were 13.11% and 12.07%, respectively.
Source: HDFC Mutual Fund, HDFC MF Factsheet — August 2026. Readers should refer to the latest official scheme documents for current information.
Don't overlook the cost of missing the rebound
There is another reason why remaining invested matters. An analysis by Abakkus Mutual Fund, reported by The Economic Times in September 2026, examined NIFTY 50 TRI returns from April 2005 through August 2026.
It reported a 13.55% CAGR for an investor who remained invested throughout that period. According to the same analysis, the CAGR fell to 9.65% when the 10 best days were missed, 4.61% when the 30 best days were missed, and 0.94% when the 50 best days were missed.
| Best days missed | Reported CAGR |
|---|---|
| None | 13.55% |
| 5 days | 11.21% |
| 10 days | 9.65% |
| 30 days | 4.61% |
| 50 days | 0.94% |
These figures are specific to the stated period and methodology; they should not be interpreted as a forecast.
So, is this market timing?
Not in the traditional sense.
Traditional market timing attempts to answer: When should I enter? When should I exit? Where is the bottom? Where is the top?
The approach discussed here asks a different question:
That is a more manageable question. You don't need to know whether a 15% decline will eventually become 25%. You need a framework that determines how much, if any, additional capital you are prepared to deploy at different levels.
A simple way to think about it
The PlanNivesh perspective
We often hear:
That remains an important principle for long-term investors.
But perhaps there is another way to look at it.
You don't necessarily have to choose between time in the market and using market corrections.
You can combine them.
Time allows compounding to work.
Corrections may create the opportunity.